European retail banks should rethink their business models to secure future growth – PwC Analysis
Net interest income remains the primary driver of profits, but no one can guarantee how long this momentum will last. Banks that use today’s earnings to diversify fee and commission income, modernize distribution, scale artificial intelligence, and improve capital efficiency will be better positioned for the next phase of retail banking.
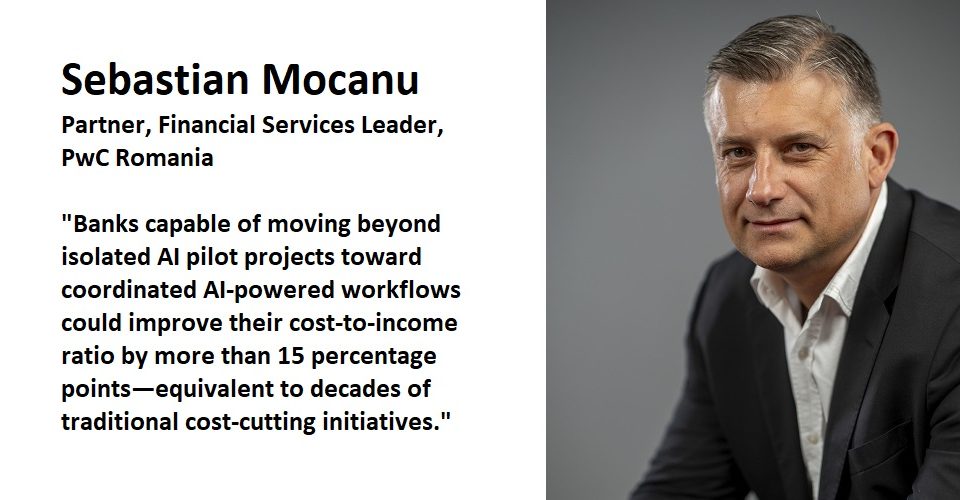
By Sebastian Mocanu, Partner, Financial Services Leader, PwC Romania.
European retail banks ended last year with 3% revenue growth and a 6% increase in operating profit, while costs rose by only 1%. These results create a timely opportunity for banks to redesign their business models with a view toward 2030, according to the latest Retail Banking Monitor published by Strategy&, PwC’s global strategy consulting business.
However, much of the recent performance remains cyclical, driven by favorable interest rate dynamics rather than by fundamentally new business models. Net interest income continues to be the dominant engine of profitability, but there is no certainty about how long this momentum will last. Since 2021, revenue per customer at European banks has increased by 27.3%, while costs have risen by only 6.2%, indicating that today’s prosperity has been built almost entirely on revenue growth rather than structural cost reforms.
At the same time, competitive pressures are intensifying. Competitors are attracting new customers, core investment products are migrating to alternative providers, and artificial intelligence is beginning to separate industry leaders from the rest.
The Gap Between European Markets Continues to Widen
France and the United Kingdom continued to benefit from higher interest rates, recording net interest income growth of approximately 14% and 12%, respectively. Meanwhile, the Nordic countries, Belgium, and Poland have already shifted toward business models centered on fee-based income, where growth approached 10%. This suggests that banks’ strategic business choices—not only the macroeconomic environment—are increasingly determining which institutions outperform their peers.
Romania’s banking sector has advanced even faster than the European average. According to the National Bank of Romania’s Annual Report, gross assets reached RON 996.1 billion at year-end, up 8.8%, while net profit totaled RON 15.4 billion.
Against this backdrop, Romanian banks appear to be in a particularly strong position. Return on equity reached 17.6%, the capital adequacy ratio stood at 25.8%, well above the European average of 20.4%, liquidity indicators remain among the strongest in the European Union, and the cost-to-income ratio of 48.9% compares favorably with the 51% average across key European banking markets.
Moreover, Romanian banks appear to have already embraced the Strategy& approach. Net fee and commission income increased by 27.1% last year—roughly eight times faster than net interest income, which grew by only 3.3%.
On the cost side, however, administrative expenses rose by 12%, partly driven by the doubling of the turnover tax from 2% to 4%. According to the National Bank of Romania, this tax is expected to amount to RON 2.1 billion in 2025.
Structural Vulnerabilities Remain
Despite their strong performance, several vulnerabilities persist. The non-performing loan ratio increased to 2.7%, while the European average declined to 1.8%. The deterioration was primarily driven by corporate lending, although the 62.4% provisioning coverage ratio remains the highest in the European Union.
Romania’s loan-to-deposit ratio of just 66.2%, compared with the European average of 104.8%, highlights the significant untapped lending capacity on banks’ balance sheets. Meanwhile, exposure to government securities has increased to 27.9% of total assets, further strengthening the link between the banking sector and public finances.
Looking Ahead to 2030: AI Will Redefine Banking
The Strategy& analysis shows that banks capable of moving beyond isolated AI pilot projects toward coordinated AI-powered workflows could improve their cost-to-income ratio by more than 15 percentage points—equivalent to decades of traditional cost-cutting initiatives. An end-to-end automated mortgage lending process, for example, can be reduced from several weeks to just a few days.
Banks that fail to keep pace risk developing a structural cost disadvantage, particularly as Europe’s leading institutions already operate with cost-to-income ratios of around 36%, well below the average across the banks analyzed.
The more significant disruption, however, will come from AI agents capable of acting autonomously on behalf of customers. This is no longer theoretical. In 2025, Mastercard, together with Santander, completed Europe’s first payment executed entirely by an artificial intelligence agent.
Once such AI agents begin managing customers’ liquidity, rebalancing investment portfolios, and automatically moving funds to higher-yielding products, many of the margins banks have long taken for granted—from idle deposit balances to high-fee investment products—are likely to come under pressure.
The key question raised by the report—and one banks can no longer postpone—is who will own the customer’s financial agent. If the primary customer interface belongs to a technology platform, banks risk becoming little more than invisible infrastructure operating behind someone else’s screen.
The competitive pressure is already visible in the market. Revolut estimates that one in every three new accounts opened in Europe belongs to the company.
Five Priorities for the Banking Industry by 2030
Strategy& recommends that banks build their 2030 strategies around five key priorities:
. Diversifying revenue through fees and commissions;
. Completing the transition to digital sales;
. Embedding artificial intelligence as a productivity tool across core banking functions;
. Preparing for the widespread adoption of AI agents; and
. Adopting asset-light operating models, in which banks rely more heavily on technology, outsourcing, and strategic partnerships rather than traditional balance-sheet-intensive assets, both to accelerate growth and improve capital efficiency.
Greater AI Adoption Also Brings Greater Risks
As AI adoption accelerates, so do the associated risks. The National Bank of Romania notes in its annual report that rapid digitalization and the increasing use of artificial intelligence are creating a more complex risk profile for banks. In this environment, a cyber incident is no longer merely an operational disruption—it can trigger rapid deposit withdrawals and threaten banks’ liquidity, making stronger supervisory oversight essential in the years ahead.