Personal AI assistant Instinct just gave AI agents their own spending money
And this could become a BIG deal for Visa, Mastercard, and the banks.
a linkedin post by Marcel van Oost, founder of Connecting the Dots in Fintech
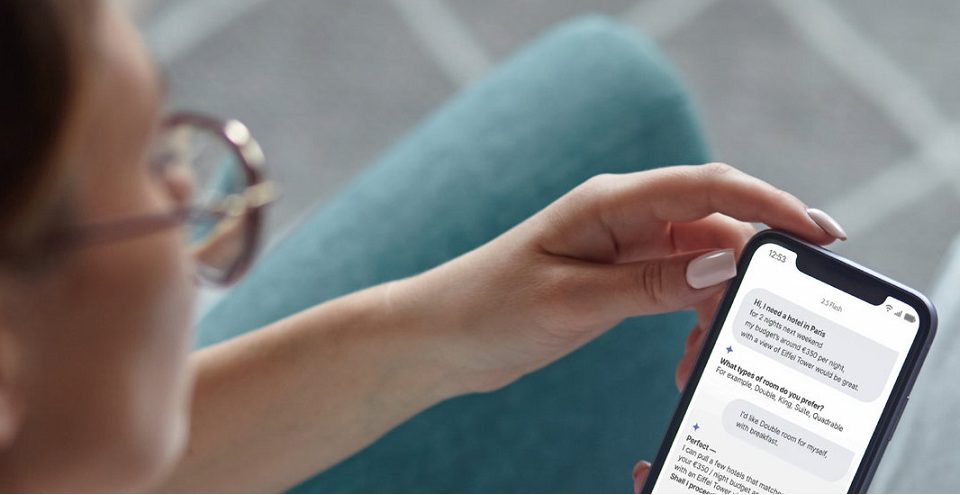
In the demo below 👇, a user loads $700 into a wallet, sets spending limits, and asks an AI agent to order lunch every day for a week, followed by concert tickets.
Here’s what happens behind the scenes:
→ Stablecoins are held in a Privy wallet on Tempo
→ Stripe converts the stablecoins into US dollars when a purchase is made
→ The dollars move into a prepaid account/wallet at Lead Bank
→ A Visa virtual card is used to complete the transaction
→ The merchant receives payment through the existing card network, without needing a crypto wallet
But here’s where things get REALLY interesting.
Stripe and the card networks have different visions for how AI agents should pay.
As Yueqi Yang reported in The Information, Stripe’s growing role in AI shopping is raising concerns among Visa and Mastercard: Stripe’s AI Shopping Lead Puts Card Giants on Edge.
Here’s why:
💳 Stripe’s approach:
In its virtual-card model, Stripe can create a single-use card for an AI agent to make a purchase.
The agent uses that virtual card to pay the merchant, while Stripe separately charges the consumer’s original payment method to load the wallet.
That means Stripe sits between the consumer and merchant, potentially gaining greater control over payment routing and transaction data.
💳 Visa and Mastercard’s preferred approach:
Instead of issuing a separate virtual card, the networks want AI agents to use secure digital tokens linked directly to consumers’ existing cards.
The agent can make authorized purchases without accessing the actual card number.
Crucially, the consumer’s existing bank and card network retain greater visibility into the transaction, helping with fraud detection, disputes, and security.
Visa calls its solution Visa Intelligent Commerce, while Mastercard has Mastercard Agent Pay.
And here’s the bigger picture.
Both approaches still rely on existing payment infrastructure.
But the battle is increasingly about who controls the customer relationship, transaction data, and choice of payment provider.
Stripe could become the default payments infrastructure for AI platforms, while Visa and Mastercard want to preserve the role of existing cards and issuing banks.
Will banks and payment networks increasingly become infrastructure suppliers to AI platforms that own the customer relationship?
What do you think?
Follow the link to see the demo.