BIS report: Circular relationships among AI firms
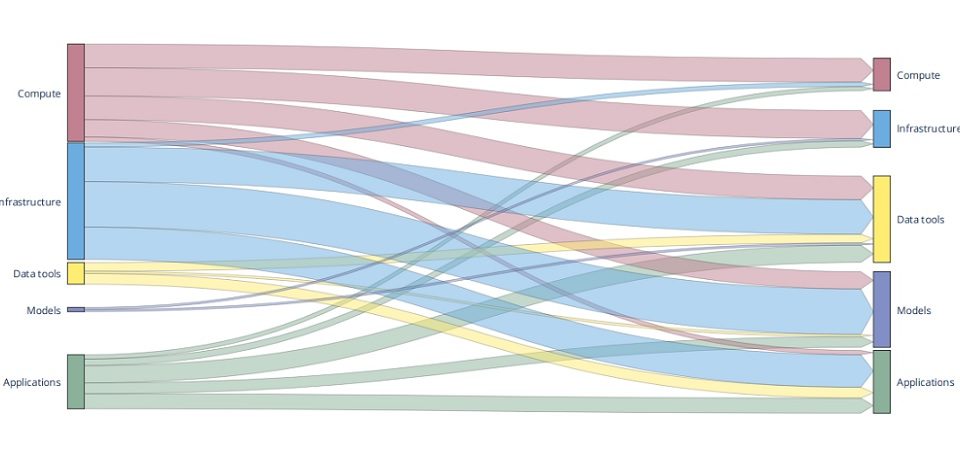
The authors of the BIS report, identified 1,246 AI firms and classified them into five supply chain layers (compute, infrastructure, data tools, models and applications). The report uncovers 972 (almost 80%) intra-AI investment relationships between 2021 and 2025. An intra-AI investment relationship is defined as circular when the investor and target firms are also connected in a commercial relationship.
Key takeaways
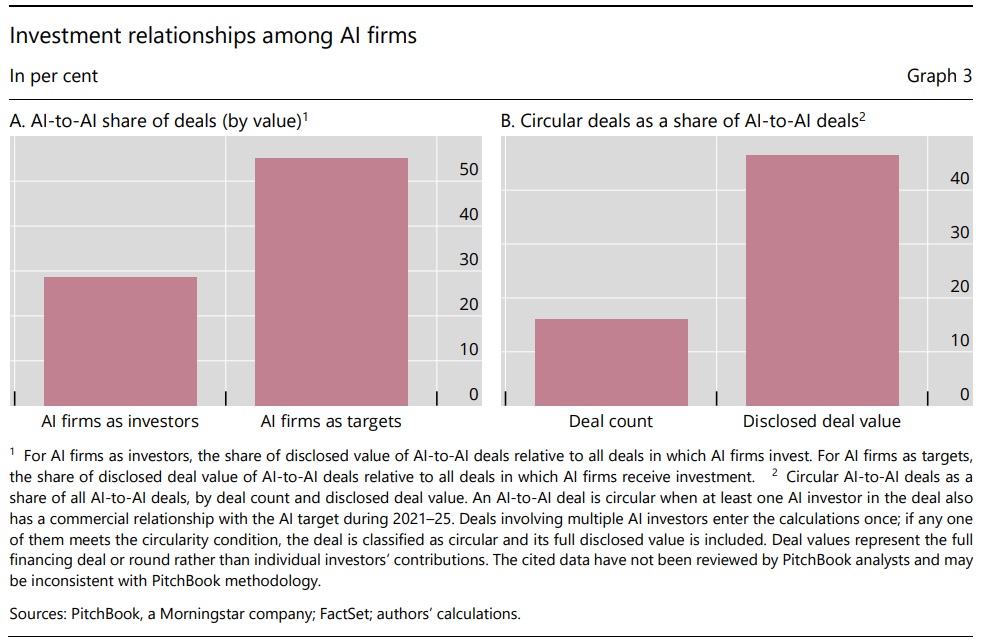
- Between 2021 and 2025, 28.7% of artificial intelligence (AI) firms’ investment deals (by deal value) involved a target company that was also an AI firm, while 55.2% of incoming investments in AI firms came from other AI firms.
- Of all the AI-to-AI investment deals between 2021 and 2025, 16.1% (by deal count) and 46.4% (by deal value) also involved commercial supply chain relationships between the investor and target firms.
- Circular investment relationships reflect key economic features such as the need to secure critical inputs and the presence of information asymmetries, yet they entail macroeconomic risks and increase opacity.
Investment in artificial intelligence (AI) has reached an extraordinary scale. The largest AI firms collectively plan to spend hundreds of billions of dollars on AI infrastructure in 2026, and capital expenditure on AI has become macroeconomically significant in many economies. A meaningful share of this capital flows through firms that serve simultaneously as suppliers of inputs and investors in firms that buy those inputs. When financing relationships and commercial relationships overlap, a “circular” investment structure emerges.
Using new data on AI firms, investment deals and supply chain linkages, this Bulletin documents investment patterns among the largest AI firms globally, focusing on circular investment relationships. It explains the rationale for such relationships, discusses why they are especially likely among AI firms and explores possible macroeconomic implications.
Defining and measuring circularity in AI investments
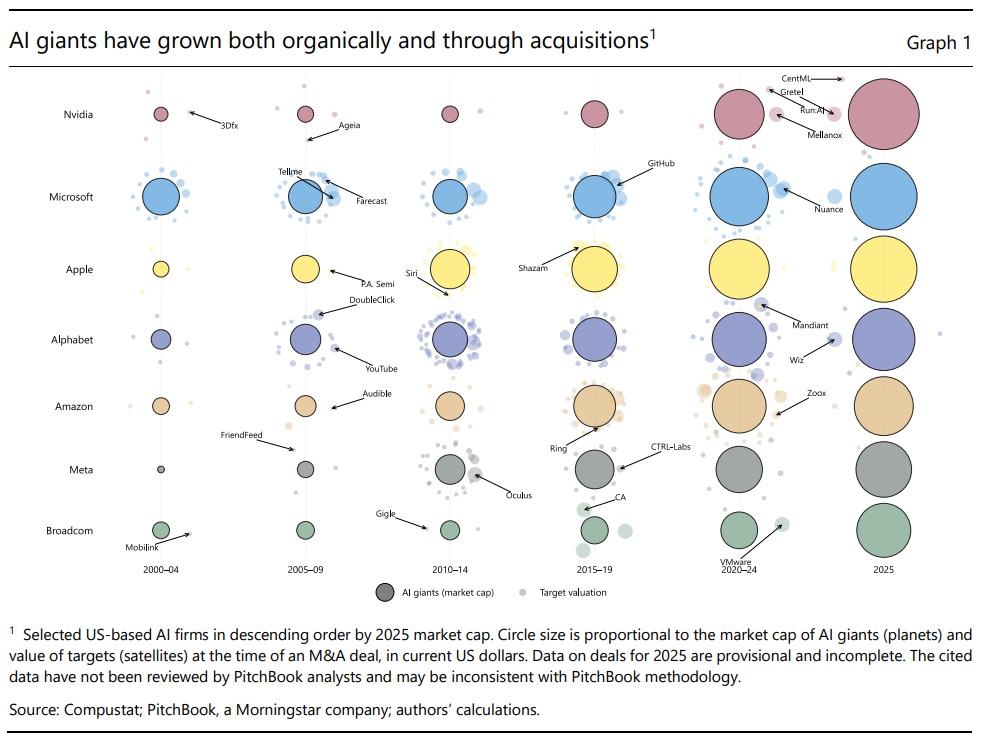
In the last two decades, a few firms have grown dramatically and transformed into key providers of AI products and services. A significant part of that growth has come from investment deals, eg mergers and acquisitions (M&A), equity financing or joint ventures.
As shown in Graph 1, the average five-year market capitalisation (market cap) of the largest US-based AI firms (represented by the central circles) rose quickly over 2000–25, and particularly after 2015. This reflects both organic growth and their investment in other companies within the ecosystem (the surrounding “satellite” circles in the graph, which represent acquisition targets of the AI firms). Many of the target firms of such acquisitions are AI firms themselves.
This Bulletin focuses on one particular type of AI investment relationship: those that are circular. An investment relationship established between two AI firms over 2021–25 is defined as circular if the firms also share a supplier-customer relationship at any point in the same period.
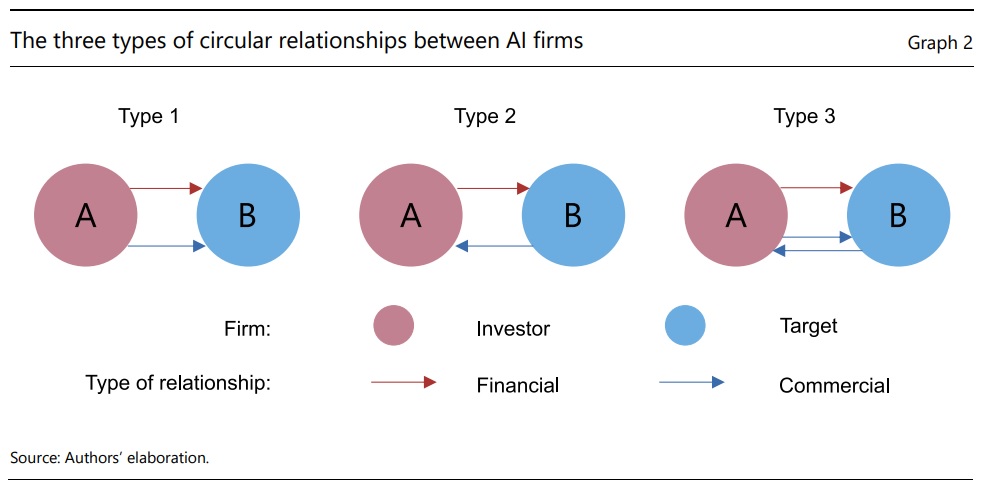
1 Three types of circular investment relationships are possible (Graph 2). The first is when the AI firm that invests in a target AI company also supplies inputs (goods or services) to it (type 1). In this case, capital and goods or services flow in the same direction. The second type occurs when capital and goods or services flow in opposite directions, ie a customer is financing its supplier (type 2). The third type involves a reciprocal commercial relationship, with goods or services flowing in both directions (type 3).
We use new data from three sources to quantify these investment relationships for major AI firms. We start with a universe of 1,246 AI firms classified into five supply chain layers (compute, infrastructure, data tools, models and applications) as in Rishabh and Shreeti (2026).
Second, we extract financing information for these firms from PitchBook, a Morningstar company (hereinafter, referred to as “PitchBook”), which contains investment (equity and debt) deal-level information for all the AI firms.2
The third component of our data comes from FactSet and includes information on the presence and direction of commercial relationships between firms. Finally, we conduct extensive manual checks to ensure that no commercial or investment relationships are excluded, to the extent possible.
This uncovers 972 intra-AI investment relationships between 2021 and 2025. An intra-AI investment relationship is defined as circular when the investor and target firms are also connected in a commercial relationship (in either or both directions) at any point between 2021 and 2025. Approximately 28.7% of investing AI firms’ targets (by deal value) are other AI firms (Graph 3.A). Conversely, 55.2% of AI firms’ incoming investment value comes from other AI firms (Graph 3.A). Moreover, 16.1% of deals (and 46.4% of intra-AI deal value) occur between AI firms that also share a commercial supply chain relationship (Graph 3.B).3 In terms of relationship direction, most involve an AI firm that invests in and supplies its products to another AI firm (64%). These numbers suggest that a significant portion of financing and commercial relationships in AI are self-referencing.
Economic implications of circular investment relationships
Circular investment relationships in AI involve some of the largest firms globally. While these structures can address contracting problems at the firm level, their highly intertwined and capital-intensive nature can also translate into macroeconomic risks. These come on top of the existing risks of over-investment and debt financing in the ongoing AI boom.
First, circular relationships make reported demand partly endogenous to firms’ own financing decisions. For example, when a supplier finances a customer, part of the supplier’s revenue growth reflects its own capital investment, rather than organic final demand. This makes it harder for investors, lenders and supervisors to gauge what part of the current AI boom is based on organic demand.
The parallel with the telecommunications boom of the late 1990s is instructive: upstream equipment vendors such as Lucent and Nortel financed network operators so that the operators could buy the vendors’ equipment. This meant that part of the equipment vendors’ reported sales was being funded by the vendors themselves. For a time, as operators expanded their networks, equipment orders also expanded and vendors booked both the sales and loans as assets. However, when operators’ own revenues failed to materialise or slowed, they could neither repay the loans nor sustain the equipment purchases. Equipment vendors then sustained both financial losses and a loss of sales. Such dynamics may also play out in AI if revenue growth and end user demand fall short of firms’ expectations.5 Amid heightened AI-driven global equity valuations, this could drive significant financial market volatility.
Second, circular relationships can increase correlations between firms’ commercial and financial exposures, with a potential to amplify spillovers during periods of stress (IMF (2026)). An investor that is also a supplier is exposed to the same counterparty twice: a shock to the customer reduces both the value of the equity stake and future product revenues.
Because circular deals are concentrated among a small number of very large firms in the upstream layers of the supply chain, adverse shocks could propagate through commercial and financial channels simultaneously, potentially amplifying contagion. These risks may be magnified by the growing use of private credit and special purpose vehicles to finance AI
infrastructure, which can create hidden leverage and interconnected exposures that amplify financial stress during downturns.
Third, these circular arrangements tend to be opaque, making monitoring and supervision difficult. Many of the firms involved in AI are private and may disclose limited information. Even where firms are publicly listed, deal terms can often be complex, mixing cash investments with long-term purchase commitments and guarantees on the value of the underlying assets. Residual value guarantees (RVGs) are one example, where the guarantor pledges to cover any shortfall in an asset’s worth (such as chips or data centre equipment) after a fixed period. These contingent commitments sit off balance sheet and only materialise during a downturn – when a guarantor is least able to absorb them. As such, reported deal values may not capture the whole picture, and headline figures can differ substantially from disbursed amounts. Moreover, many of these firms reside in different sectors and jurisdictions, making it difficult for a single supervisor or regulator to monitor these risks.
Read the full document here: BIS Bulletin no.137 – Circular relationships among AI firms